Jason Mercier: Washington’s I-645 would repeal the new 9.9% income tax with a current statutory million-dollar exemption
Washington voters should repeal the "millionaire's tax" this November, which would hurt the state's competitive advantage and will eventually apply to everyone.

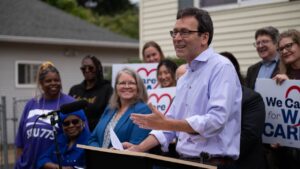
Let's Go Washington supporters gather in Tumwater to turn in signatures for the initiative to repeal Washington's 9.9% income tax. (Let's Go Washington)
(Let's Go Washington)
This November, Washington voters will decide whether to enact I-645. This proposal would repeal a new 9.9% income tax, with a current statutory exemption of one million dollars, that is scheduled to take effect in 2028. Despite the Washington State Supreme Court repeatedly ruling that this type of income tax is unconstitutional, the legislature imposed it this year anyway while attaching an emergency clause to prevent a voter referendum.
Unable to pursue a referendum, opponents of the new income tax qualified I-645 for voter consideration instead. A separate constitutional legal challenge to the new income tax is also underway in the courts. Washington voters have overwhelmingly rejected ten straight income tax proposals.
For nearly 100 years, the state Supreme Court has ruled that Washingtonians own their income, meaning it is property. This is why a graduated income tax (non-uniform and at more than 1% of value) requires a constitutional amendment. The income tax enacted has a 9.9% rate.
A slippery slope
Because the income tax subject to repeal by I-645 was enacted as a regular statute and not submitted as a constitutional amendment, any claims that the tax and its rate will not expand to more taxpayers deserve skepticism. The history of income taxes across the country is to start limited to high earners and then expand to more taxpayers. Washingtonians should expect the same to happen here.
Income tax rate and bracket creep are especially concerning when realizing that Sen. Pedersen, sponsor of the new income tax, said this about repealing the I-2111 state and local income tax ban adopted in 2024: “That was — what did Mary Poppins call that? — a ‘pie crust promise.’ Easily made, easily broken. We put that language into statute, and we can amend it any time we want to. I wouldn’t take that super-seriously.”
The tax would be devastating for business
It wasn’t long ago that Washington state openly boasted about how businesses and individuals had a competitive advantage because the state didn’t impose income taxes. Washington’s Department of Commerce advertised across the country in 2012: “Choose Washington – We offer businesses some competitive advantages found in few other states. These include no taxes on capital gains or personal or corporate income.”
Now, however, the state imposes both a capital gains and a personal income tax. This dramatic course reversal, throwing away the state’s competitive advantage, is of great concern to business leaders in the state.
The Association of Washington Business warns: “Washington is already a high-cost state for families and employers, even without this new tax,” said AWB President Kris Johnson. “By adopting a state income tax, we are giving up one of our few competitive advantages with other states and regions and making Washington even more expensive for small- and medium-sized businesses, many of which are structured as S-corps and pass-through entities. If this tax is not repealed, they will have a higher tax burden and less profit for capital expansion, equipment, payroll and employee benefits. We hope voters will approve I-645 and lawmakers will get to work creating a growth agenda for the state.”
An AWB survey of Washington employers this summer underscores this concern: “Washington employers remain pessimistic about the state economy, citing taxes as their top concern and continuing to look outside Washington for expansion opportunities…”
You will be affected by the tax, even if you’re not a millionaire
Though income tax supporters say the tax will be restricted to “millionaires,” 45% of AWB employer survey respondents (22% unsure) expect the new income tax to impact their businesses.
Supporters of the new tax claim that repealing the tax will adversely impact current government services. The new 9.9% income tax in question, however, is not scheduled to take effect (assuming it survives constitutional legal challenges) until 2028, with revenues not collected until 2029. This provides lawmakers with several years to plan for future expenditures around revenues that will be available from existing sources in 2029.
By adopting I-645, voters would have the opportunity to restore the state’s “competitive advantage” of no personal income taxes while working to increase faith in Washington’s business climate.
Should voters reject I-645, the new 9.9% income tax with a current statutory exemption of one million dollars will still face legal challenges for violating nearly 100 years of state Supreme Court rulings clearly telling lawmakers that imposing this type of income tax requires a constitutional amendment.
Jason Mercier is Vice President and Director of Research of Mountain States Policy Center, an independent research organization based in Idaho, Montana, Washington and Wyoming. Online at mountainstatespolicy.org.
Follow Seattle Red on-air at 770 AM, on the Seattle Red app, and streaming audio and video on SeattleRed.com.
Related
 Rantz: Literally every claim in Pramila Jayapal's argument for a Washington income tax is a lie
 WA DOR warned income tax provisions could ‘cause political and optics issues’
 Rantz: Archie McPhee owner caves to the activist mob over the income tax in cowardly display
 Cargill: Washington’s $4 billion budget gap proves Olympia has a spending problem
 Chris Cargill: First report on Idaho ed choice tax credit shows program a monumental success
 Dave Larson: Washington needs to reform judicial election process
Comments
0 Comments